G+D Netcetera manages 1.4 billion tokens
Payment tokenization as prerequisite in e-commerce
Traditional implementation requires a separate integration for every new scheme mandate, every new capability.
The Fusion Platform changes that. Connect once through a single API or SDK — and activate new services through existing connections without disrupting production.
The Fusion Platform abstracts the complexity of individual card network implementations, of the different specifications, timelines and mandates.
Behind a consistent interface it handles all of this. Issuers gain cross-scheme security coverage without cross-scheme integration complexity.
Fraud patterns shift. New mandates are introduced. What was sufficient a year ago may be insufficient today.
The Fusion Platform is adaptive: as new capabilities become available, they are added for all connected issuers. Security becomes living infrastructure.

Operational complexity drops. Vendor management overhead drops. When a card network introduces a new mandate, you activate it through an existing API call — not a new integration project.

Now issuers can adopt additional services without complex re-engineering. Time-to-market shrinks from quarters to weeks. The team that would have spent six months on a new integration focuses on customer-facing features instead.

Point solutions look cheaper until you count the integrations, the maintenance, the compliance projects, and the internal resource required to keep multiple vendor relationships current. The G+D Netcetera Fusion Platform consolidates all of this, with security monitoring runing 24/7.

The Fusion Platform roadmap includes continuous expansion. Issuers who connect today will have an access to everything new, without new procurement or re-integration.
The foundation of the Fusion Platform.
Tokenization and lifecycle management services from Visa Token Service, Mastercard Digital Enablement Service, and additional major card networks — delivered through a unified API.
Supports all Token Requestors: OEM wallets (Apple Pay, Google Pay, Samsung Pay), merchant card-on-file, Click to Pay, and bank-issued wallets. No need to connect to each network's tokenization service separately.
Scheme-provided Alias Directory Services, accessible through the same Fusion Platform connection.
Alias directories are increasingly central to A2A and P2P payment flows, VoP-adjacent verification, and the emerging payment passkey ecosystem.
Having these available through an existing connection means issuers are ready to activate them when scheme mandates or market conditions require it — without opening a new integration project.
Scheme-offered payment passkeys, delivered through the Fusion Platform as part of the same unified security infrastructure.
As FIDO-based authentication becomes the standard for secure payment confirmation — and as scheme mandates begin to require it — issuers connected to the Fusion Platform can activate passkey support through their existing connection.
No separate FIDO integration. No new vendor relationship.
Seamless and secure push provisioning of cards into payment apps and network-based wallets including Google Pay, Apple Pay, Samsung Pay, and Click to Pay.
The Fusion Platform manages the provisioning flow, the token lifecycle, and the ongoing management of digitalized card accounts, so issuers can expand their wallet presence without expanding their integration footprint.
Strengthen e-commerce transactions by enabling card-on-file merchant payments to be processed through tokens rather than raw card data.
The Fusion Platform manages the token lifecycle for e-commerce use cases alongside the wallet and in-app flows — giving issuers a single operational view of all their digitalized card accounts, regardless of where or how those accounts are being used.
The Fusion Platform is built with A2A payment card network support as part of its roadmap.
As account-to-account payment flows mature and require the same security infrastructure as card-based payments — tokenization, alias management, authentication — connected issuers will be able to extend their existing Fusion Platform connection rather than building separate A2A security infrastructure.
The platform is ready before the mandate arrives.


Payment fraud has never attacked through a single vector, and modern payment infrastructure should not defend against it through a single point solution either. The G+D Netcetera Fusion Platform gives issuers what competing point solutions cannot: a complete, evolving security infrastructure that absorbs new scheme mandates and new fraud capabilities without requiring a new integration project every time the landscape shifts."
- Klaus Sparrer, Tokenization Expert, G+D Netcetera
A tokenization service does one thing: it converts card numbers into tokens. The Fusion Platform does that and it also delivers Alias Directory Services, payment passkeys, XPay wallet provisioning, e-commerce token management, and A2A security capabilities through the same single connection. The difference matters commercially: with a point tokenization service, every new scheme mandate or new security capability requires a new integration project. With the Fusion Platform, it requires an API call to activate a service that is already connected. The integration is the same. The scope expands.
Primarily issuers and fintechs who want to deliver secure digital payment experiences without building and maintaining multiple separate integrations. This includes established banks launching digital wallet capabilities, challenger fintechs who need enterprise-grade security without enterprise integration complexity, and any issuer who has experienced the pain of a scheme mandate arriving faster than an integration project can be completed. The Fusion Platform is also relevant for any organisation that wants to add passkeys, A2A security, or emerging scheme capabilities to their existing tokenization infrastructure without starting again.
Issuers connect to the Fusion Platform once — either via API (server-to-server) or SDK (client-side). The platform maintains certified, live connections to Visa Token Service, Mastercard Digital Enablement Service, and other major scheme security services. When an issuer wants to activate a new capability — say, payment passkeys when their card network announces a mandate — they make an API call to activate that service. The Fusion Platform already has the scheme connection in place. There is no new certification, no new vendor onboarding, no new integration project. The capability is live in days, not months.
It means the Fusion Platform presents a consistent interface to the issuer, regardless of which card network's services are being used behind it. All mayor card networks have different tokenization specifications, different mandate timelines, different technical requirements. The Fusion Platform abstracts all of this: the issuer sees one API, one set of documentation, one operational process. When a new domestic scheme or A2A network is added to the platform, the issuer's integration does not change. The platform handles the scheme-specific complexity invisibly.
The Fusion Platform holds PCI DSS Level 1 Service Provider certification, the highest level of PCI compliance for cardholder data processing. G+D Netcetera is certified as a Visa Token Service Provider and Mastercard Digital Enablement Service Provider. G+D Netcetera is an EMVCo Technical Associate, contributing directly to the development of global payment security specifications. ISO 27001 certification covers all G+D Netcetera divisions (September 2025). SOC 2 Type II attestation covers operational controls. The compliance framework supports GDPR, regional data sovereignty requirements, and issuer DORA third-party risk obligations.
Continuous expansion across four areas. First, additional card network coverage: international schemes, local and domestic schemes, and emerging A2A payment card networks. Second, new security services: AI-powered fraud detection integration and real-time risk scoring capabilities. Third, emerging authentication: passkeys (already available through scheme-offered integrations) and next-generation authentication methods as they reach scheme mandate status. Fourth, A2A payment security: as account-to-account flows mature and require tokenization-grade security infrastructure, the platform will extend to cover them through the same single connection. Issuers connected today will access all of this through their existing integration.
G+D Netcetera's bank-issued NFC and eSE wallet platform. The Fusion Platform is the connection layer that provisioning tokens into CloudPay depends on. When an issuer deploys both, they get end-to-end control: the wallet experience, the payment token, and the entire provisioning infrastructure — all from a single partner.
The Fusion Platform secures the token. The 3DS Issuer Service secures the transaction. When combined, issuers have coverage across the full cardholder authentication journey — from digital card issuance through to transaction-level verification. Two products, one security posture.
Payment tokenization as prerequisite in e-commerce
First-party misuse is now the world’s leading type of fraud, yet it is almost impossible to spot at checkout. Discover why friendly fraud is rising, what it costs the payments industry, and how better data sharing could help distinguish genuine disputes from deliberate abuse.
G+D Netcetera wins two Juniper Awards 2026 for fraud prevention and digital wallets, as banks rethink their systems landscape for future payments
3DS and SCA are working as designed. So why is UK payment fraud still rising?
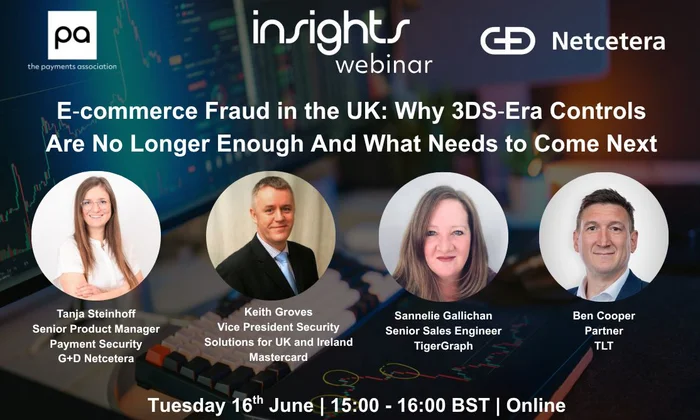
This free on-demand webinar with G+D Netcetera and The Payments Association UK explores why 3DS alone is no longer enough, and how banks can use earlier intervention, cross-channel intelligence and secure data sharing to make fraud prevention more proactive.
G+D Netcetera Becomes an Official AWS Partner, Strengthening Cloud-Based 3DS Solutions
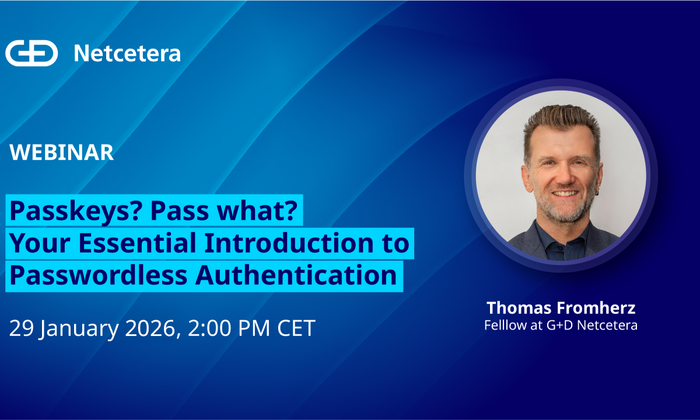
Your Essential Introduction to Passwordless Authentication. Tired of password resets, phishing attacks, and frustrated customers? It's time to discover passkeys—the authentication technology that's making passwords obsolete.
Payment trends for 2026: digital identity wallets, network tokenisation, AI fraud prevention, VRPs, embedded finance and payment orchestration.
In our latest podcast episode, payment network expert Michael Schoch explains how Secure Remote Commerce (SRC) is creating new growth opportunities for domestic card networks.
This Tech Tribe episode gives a rare look into how advanced fraud prevention works when every second counts — and how the right expertise can turn a crisis into a controlled situation.
CEO Carsten Wengel sits down with Martina Forster, Portfolio Owner for Secure Digital Payments at G+D Netcetera, to explore the evolving world of digital payments: from 3-D Secure to instant payments, Big Tech, and digital identity.
Protecting the business and customers from invisible threats
Make Instant Payments a success with G+D Netcetera, as your strategic partner
Remember the last time you abandoned a purchase because you couldn’t find your card? How much time, energy, and mood did you waste filling in the requested information? Ultimately, you just left your purchase because it was too time-consuming, data-consuming, and energy-consuming. Sound familiar? That’s exactly why Click to Pay was created. In this episode with Suzana Kordumova Nikolova, we explore what makes Click to Pay different from Apple Pay and Google Pay, how it enhances security, and why businesses adopt it.
Passwords are becoming a thing of the past. Passkeys deliver a safer, faster, and more seamless way to log in and approve payments. Payment expert Nakjo Shishkov explains how passkeys, 3DS, Click to Pay, and FIDO authentication set new standards for secure digital experiences. Learn how passkeys work, why they improve security, and how they drive better user journeys and higher conversion rates.
Wach the Click to Pay webinar featuring G+D Netcetera, Worldline, and Visa experts.
Maximizing Trust and Efficiency: G+D Netcetera expands ISAE 3402 certification to cloud services