G+D Netcetera manages 1.4 billion tokens
Payment tokenization as prerequisite in e-commerce
APP fraud costs Europe up to 2.4 billion euros annually. Misdirected payments add to the bill. Both happen in the same moment: when a payer enters an IBAN and a name and presses send.
VoP intercepts that moment, checking the name matches the account, in real time, before the money moves.
Mandated across Europe under PSR, IPR, and SEPA Instant Credit Transfer regulations.
Over 100 million accounts covered. More than 1 million verification requests processed every day, with observed peaks above 2 million.
95% of responses returned in under 500 milliseconds. 40+ financial institutions live.
This is an infrastructure already running at national scale.
A solution built to meet your current and future needs across channels, payment types, and markets.
The API integrates with what you already have.
And the platform evolves as mandates change, so you do not have to rebuild.
VoP initiatives in the Netherlands and the UK delivered an 81% reduction in all-cause fraud and a 67% drop in misdirected payments. PSR in the UK, IPR across the EU, and SEPA Instant Credit Transfer regulations have mandated the VoP adoption across Europe.
The most critical moment in any payment is the second before money leaves an account. VoP adds a verification step at exactly that moment, catching scams and mistakes before they become fraud claims, chargeback disputes, or regulator conversations.
28% of European mobile wallet non-users cite worries about hacked payment details as a barrier to adoption. A bank that visibly verifies payees before every transfer gives customers a reason to stay, to trust, and to recommend. VoP is the feature that shows you take their money seriously.
A banking security check that confirms the person a customer is paying is actually who they claim to be, before money leaves the account.
It verifies the beneficiary’s name and IBAN via secure, encrypted APIs based on the European Payments Council (EPC) VoP scheme rulebook. The check adds 1 to 5 seconds to the payment experience as seen by the customer. It covers both domestic and cross-border payments, consistent protection wherever your customers send money.
Mandated across Europe under PSR, IPR, and SEPA Instant Credit Transfer regulations.
When the check is complete, payers receive one of four responses.
Match: the name matches exactly, proceed with confidence.
Close match: similar but not identical, the customer sees the actual account name and decides.
No match: the names do not match, a clear warning is shown before the customer decides whether to continue or cancel.
Unable to perform: if no response arrives within 5 seconds, the customer is informed in line with the VoP rulebook.
Our solution supports single and bulk VoP checks through web and API interfaces.
For bulk checks we offer a synchron and asychron process in the pain-Format.
With a single API for global connectivity
VoP scope is expanding rapidly as compliance mandates and fraud risks grow. G+D Netcetera has already normalised to the API standards required for cross-scheme interoperability, so as VoP expands to new markets and payment corridors, your integration does not need to change.
Built on 200 million German accounts records through our KWG24c service.
As a certified Trust Center, G+D Netcetera issues the PSD2 QWAC certificates required for VoP, removing a step that trips up most implementations. Financial institutions using our VoP can go live significantly faster, with far less integration effort.
The platform delivers a match rate of approximately 70%, reflecting real-world name data across markets and payment corridors.
A web portal supports manual VoP checks for offline channels, which is essential for branch and call-centre interactions.
Portal with dual control principle used for VoP analytics, manual VOP requests and customisation.


Before completing a transaction, payers receive immediate feedback: match, close match, no match, or unable to perform. Simple, transparent, and confidence-building — at the moment it matters most.
The entire verification process adds just 1 to 5 seconds to the payment experience, the time the customer sees. The underlying API response arrives in under 500 milliseconds in 95% of cases. Customers get the speed of instant payments and the assurance that their money is going to the right place.
VoP works whether customers pay via mobile, web, or in-branch. The protection follows the customer wherever they pay, consistent, reliable, and invisible in the best possible way.
"We deliver you fully regulatory-compliant solutions with knowledge and expertise in fraud prevention. And we stay with you all the way to protect your cardholders. The least we can do as players in this ecosystem is to join forces, collaborate and align among ourselves in this fight against billions of losses."
"The financial institutions that will thrive in this new era are those that view instant payments not just as a technical upgrade, but as a foundation for reimagining customer relationships and business models. The future belongs to those who can balance security with seamless user experience while creating value beyond the transaction itself."
Our API-first architecture connects smoothly with your existing payment infrastructure, core banking systems, payment hubs, and mobile banking apps. It supports multiple standards and formats, and is designed to add security without adding complexity. Easy to implement, straightforward to maintain, and built to scale with your business.
The same infrastructure that returns 95% of API responses in under 500ms runs yours.
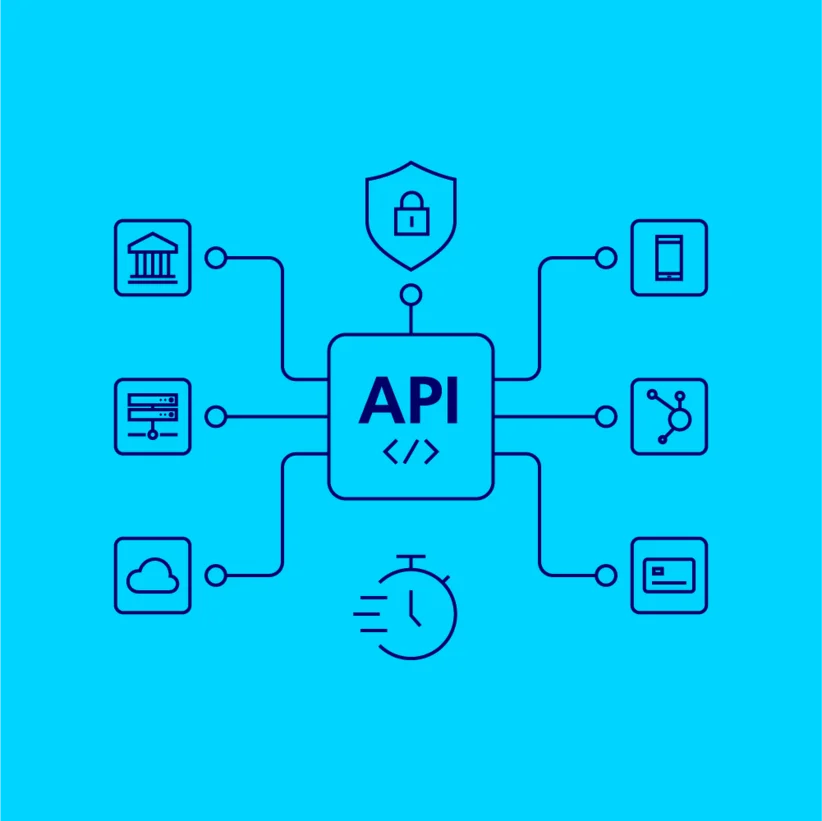
G+D Netcetera's broader fraud prevention framework goes beyond VoP. Our SDK analyses how users interact with their devices during registration and at the point of payment, creating unique behavioural profiles that are difficult for fraudsters to replicate. Our systems monitor payment patterns in real time, identify anomalies in milliseconds, and adapt as new fraud tactics emerge, keeping pace with instant payments.
An essential layer of customer protection, a banking security check that confirms the recipient's identity before a payment is processed. It verifies that the account number (IBAN) and the name entered by the payer match the actual account holder at the recipient's bank. VoP is now mandated across Europe under the Payment Services Regulation (PSR) in the UK, the Instant Payments Regulation (IPR) across the EU, and SEPA Instant Credit Transfer requirements.
A VoP request requires the payee's IBAN or other applicable account identifier, the payee's name, the identity of the requesting payment service provider, and any additional details needed to confirm accuracy. The G+D Netcetera solution handles all of these in a single API call, returning a clear result — match, close match, no match, or unable to perform — with 95% of API responses arriving in under 500 milliseconds.
Three things that are hard to replicate: scale, expertise, and the managed service model.
Scale: over 100 million accounts, 1 million+ daily requests, 40+ financial institutions live , production-grade infrastructure already running at national scale.
Expertise: 30 years in payment security and fraud prevention. Managed service: fully hosted and operated by G+D Netcetera, with no infrastructure burden on your side, automatic updates, and a security framework that goes beyond VoP to include behavioural biometrics and real-time transaction monitoring.
The payer is informed before the transaction proceeds. They retain the choice to continue or cancel — ensuring full transparency and informed consent. For a close match result, the actual account holder name is shown, so the customer can decide with full information. If no response is received within 5 seconds, the payer is notified that the verification check is unable to perform, in line with the VoP rulebook.
Yes. The G+D Netcetera VoP service covers both domestic and cross-border payment scenarios, providing the widest available global reach. Whether customers are making transfers within a single market or sending money internationally, the same verification layer applies — consistent and reliable. The approximately 70% match rate reflects real-world name data across diverse markets and payment corridors.
Authentication that protects every card-not-present transaction. Layer 3DS onto VoP for end-to-end payment security — from payee verification to transaction authentication.
Modern, phishing-resistant authentication for banking and payments. Strengthen your customer journey with passkey-based login and strong customer authentication — the natural partner to VoP.
Full visibility and control over your token lifecycle. Securing the integrity of tokenized payment credentials.
Payment tokenization as prerequisite in e-commerce
First-party misuse is now the world’s leading type of fraud, yet it is almost impossible to spot at checkout. Discover why friendly fraud is rising, what it costs the payments industry, and how better data sharing could help distinguish genuine disputes from deliberate abuse.
G+D Netcetera wins two Juniper Awards 2026 for fraud prevention and digital wallets, as banks rethink their systems landscape for future payments
3DS and SCA are working as designed. So why is UK payment fraud still rising?
This free on-demand webinar with G+D Netcetera and The Payments Association UK explores why 3DS alone is no longer enough, and how banks can use earlier intervention, cross-channel intelligence and secure data sharing to make fraud prevention more proactive.
G+D Netcetera Becomes an Official AWS Partner, Strengthening Cloud-Based 3DS Solutions
Your Essential Introduction to Passwordless Authentication. Tired of password resets, phishing attacks, and frustrated customers? It's time to discover passkeys—the authentication technology that's making passwords obsolete.
Payment trends for 2026: digital identity wallets, network tokenisation, AI fraud prevention, VRPs, embedded finance and payment orchestration.
In our latest podcast episode, payment network expert Michael Schoch explains how Secure Remote Commerce (SRC) is creating new growth opportunities for domestic card networks.
This Tech Tribe episode gives a rare look into how advanced fraud prevention works when every second counts — and how the right expertise can turn a crisis into a controlled situation.
CEO Carsten Wengel sits down with Martina Forster, Portfolio Owner for Secure Digital Payments at G+D Netcetera, to explore the evolving world of digital payments: from 3-D Secure to instant payments, Big Tech, and digital identity.
Protecting the business and customers from invisible threats
Make Instant Payments a success with G+D Netcetera, as your strategic partner
Remember the last time you abandoned a purchase because you couldn’t find your card? How much time, energy, and mood did you waste filling in the requested information? Ultimately, you just left your purchase because it was too time-consuming, data-consuming, and energy-consuming. Sound familiar? That’s exactly why Click to Pay was created. In this episode with Suzana Kordumova Nikolova, we explore what makes Click to Pay different from Apple Pay and Google Pay, how it enhances security, and why businesses adopt it.
Passwords are becoming a thing of the past. Passkeys deliver a safer, faster, and more seamless way to log in and approve payments. Payment expert Nakjo Shishkov explains how passkeys, 3DS, Click to Pay, and FIDO authentication set new standards for secure digital experiences. Learn how passkeys work, why they improve security, and how they drive better user journeys and higher conversion rates.
Wach the Click to Pay webinar featuring G+D Netcetera, Worldline, and Visa experts.
Maximizing Trust and Efficiency: G+D Netcetera expands ISAE 3402 certification to cloud services